
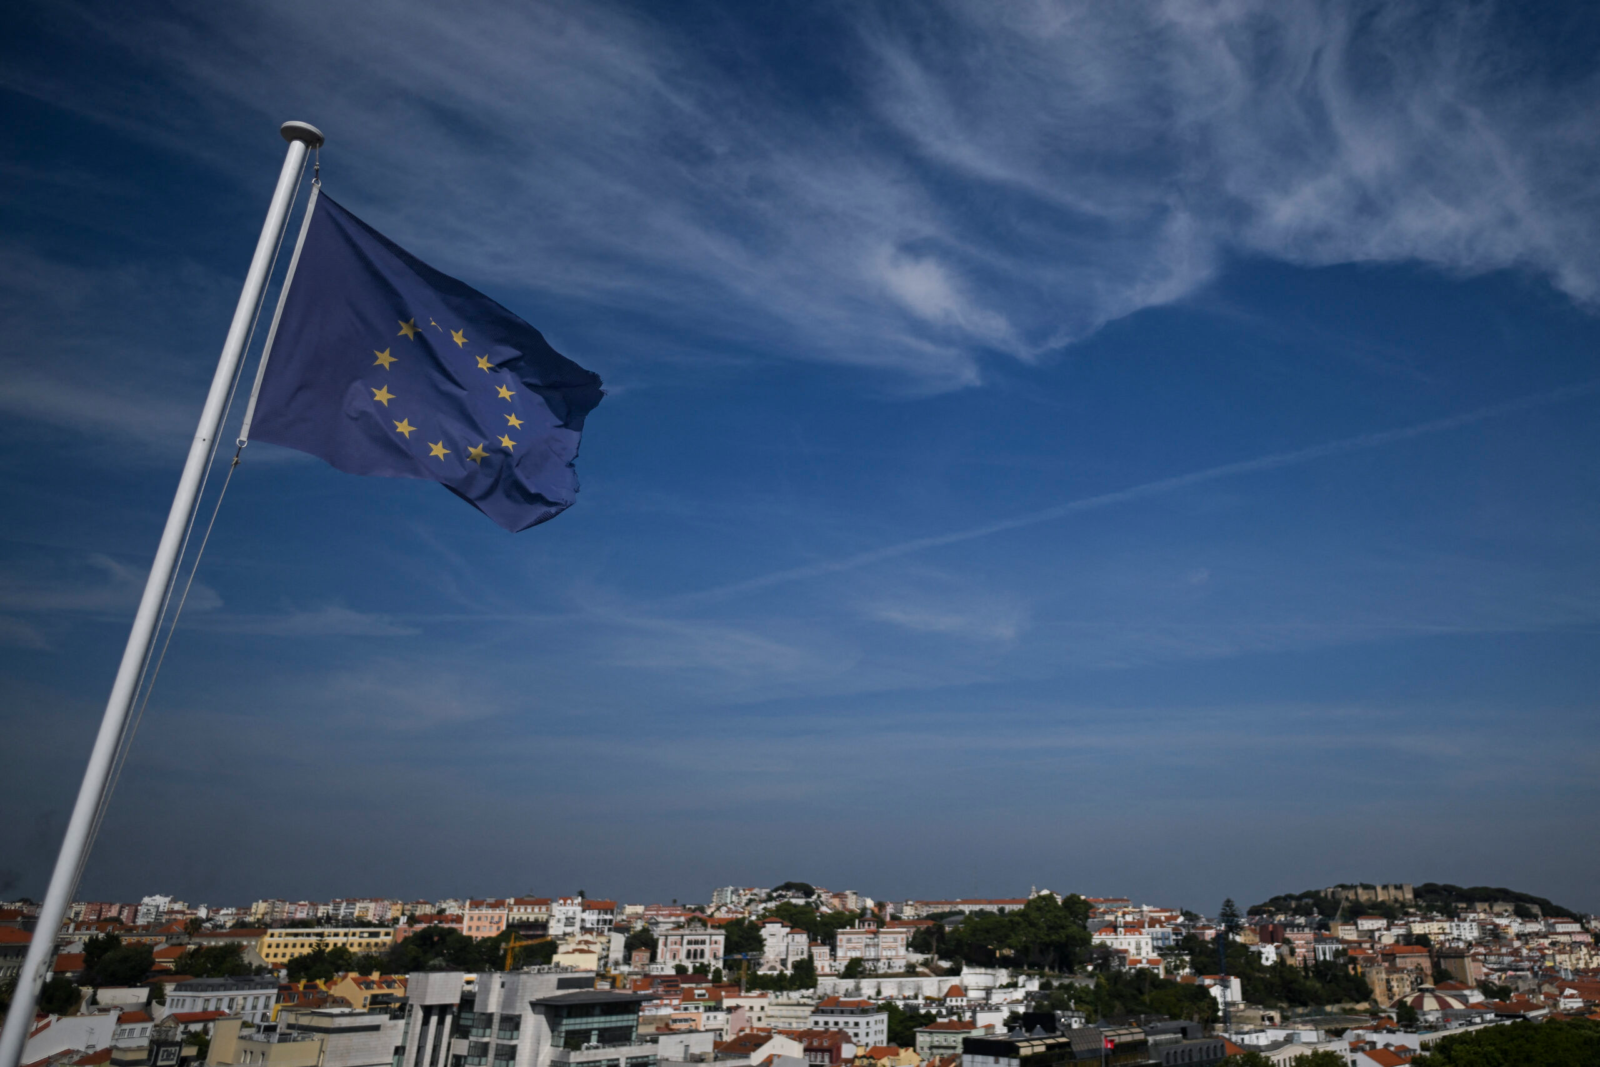
Europe’s Carbon Border Adjustment Mechanism (CBAM), which began pricing carbon-intensive imports on January 1st, 2026, could create a near-term business case for carbon capture and storage (CCS) in Africa, with exporters in sectors covered by the mechanism facing a carbon charge that may make CCS investment economically viable.
CBAM exists so that EU producers subject to the Emissions Trading System (ETS) are not disadvantaged by foreign producers facing no comparable carbon charge, covering iron and steel, cement, fertiliser, aluminium, electricity and hydrogen, with African exporters in these sectors potentially facing significant costs that could be reduced through CCS deployment. A cement and clinker producer in Algeria or Egypt that sells mainly into the EU might consider installing carbon capture facilities and developing permanent geological storage for CO₂ close to the plant, reducing the CBAM charge on its exports.
The near-term case for CCS in Africa rests primarily on exporters facing the EU’s carbon border, with John McLaughlin of Storegga arguing that lower construction and operating costs in North Africa could make CCS more competitive there than in Europe, especially for producers in Algeria or Egypt that rely on EU buyers. The mechanism creates a direct financial incentive for African producers to invest in CCS, as the carbon charge on their exports could be reduced or eliminated if they capture and permanently store the CO₂ emissions associated with their production processes.
The economics of CCS in Africa are influenced by the cost of capture technology, the availability of suitable geological storage sites, and the proximity of storage to industrial emitters, with North African countries potentially having an advantage due to lower construction and operating costs compared to Europe, while also being geographically closer to EU markets. The challenge for African producers is to assess whether the cost of CCS deployment, including capture equipment, transport infrastructure and storage development, can be offset by the reduction in CBAM charges on their exports.
Beyond the near-term opportunity for African exporters to reduce their own CBAM charges, two longer-term opportunities could emerge: the import and storage of CO₂ captured in southern Europe, and the production of carbon dioxide removal credits, with North African stores potentially serving as destinations for CO₂ shipped from southern European emitters. The first opportunity would require significant investment in port infrastructure, storage certification and cross-border regulatory frameworks, while the second would depend on the development of biomass logistics, competition for land and water, and the establishment of credible carbon removal credit markets.
The Global CCS Institute’s 2026 report notes that Africa’s CCS activity remains at an early stage, with cross-border collaboration and feasibility studies driving initial progress, while Europe’s CCS development pipeline could reach 141 million tonnes per year if projects proceed as planned, with 15 projects operating and 21 under construction. The growth of Europe’s CCS market, including cross-border agreements, CO₂ shipping and planned pipeline networks, could create demand for storage capacity in North Africa, positioning the region as a potential hub for CO₂ storage serving European emitters.
Governments can prepare now by mapping storage geology, setting up licensing rules, and including CCS needs in port plans, with the challenge being to create the regulatory, technical and financial conditions that would allow CCS projects to move from feasibility studies to commercial deployment. The African Union’s broader climate and energy agenda, including the push for local processing of critical minerals and the development of renewable energy infrastructure, could complement CCS deployment by creating the industrial base and energy infrastructure needed to support carbon capture and storage projects.
The outcome of Europe’s CBAM implementation and the development of CCS markets in Africa will depend on a range of factors, including the evolution of carbon pricing, the availability of financing, the pace of technological development and the willingness of governments to create enabling regulatory frameworks, with the potential for CCS to become a significant industry in Africa if these conditions are met. The challenge for African governments and producers is to position themselves to capture the opportunities presented by Europe’s carbon border while avoiding the risks of becoming overly dependent on external carbon pricing mechanisms.
Africa Presents is a Pan-African digital magazine and monthly publication covering politics, business, economy, culture, tech, and the stories shaping Africa and its diaspora. Visit africapresents.com and follow @AfricaPresents for daily coverage and monthly themed magazine editions.




Leave a comment