
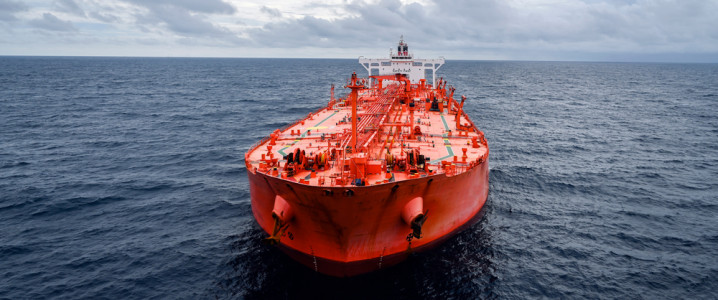
Asian oil buyers are stepping up purchases of African and Brazilian crude as tanker freight rates on Atlantic Basin cargoes fall sharply from record highs, making long-haul shipments more affordable for refiners in China, South Korea and other Asian markets.
The cost of delivering African and Brazilian crude to China has fallen by $5 to $10 per barrel from last month, according to a trader closely tracking these deals, with freight rates for very large crude carriers (VLCCs), excluding loadings inside the Strait of Hormuz, as well as for Suezmax and Aframax tankers, declining about 50 per cent from their October peaks, based on Baltic Exchange data. The sharp correction in freight rates has prompted Asian refiners to resume purchases of Atlantic Basin crude, with companies including Unipec, the trading arm of China’s Sinopec, and South Korea’s SK Energy securing cargoes and chartering vessels at significantly lower rates.
Unipec, one of the main buyers of crude from West Africa and Brazil, purchased two cargoes of Congolese Djeno crude at discounts of about $22 per barrel to dated Brent on a free-on-board basis last week, while a Chinese independent refiner based in eastern Shandong province bought 1 million barrels of Angolan Plutonio crude for delivery in late December or early January at about $15 above ICE Brent, down from premiums exceeding $20 two weeks earlier. South Korea’s SK Energy has provisionally chartered a Suezmax tanker to load at Gabon for Ulsan in December, with the transactions reflecting renewed interest in African crude as freight costs ease.
The decline in freight rates has made crude from west of the Suez Canal increasingly attractive to Asian buyers, according to analysts at consultancy Energy Aspects, with elevated premiums for rival Russian ESPO crude also supporting Chinese demand for heavier Angolan grades. The renewed demand is benefiting Congo, Angola and Gabon, whose oil must travel farther to Asia than competing barrels from the Middle East and Russia, with lower transport costs helping to offset the geographic disadvantage.
The recent freight correction has been driven by improving vessel availability following October’s exceptional market tightness, with the number of laden mainstream VLCCs and Suezmaxes in East Asia increasing by approximately 15 per cent since early September, suggesting a growing pool of vessels that could become available as they complete discharge operations, according to Vortexa shipping analyst Wanying Zhang. Freight rates surged in October as demand for tankers exceeded available supply, with Middle Eastern producers cranking up exports and requiring more vessels to conduct ship-to-ship transfers outside the Strait of Hormuz to avoid attacks linked to the US war on Iran, while a switch by Chinese independent refiners to non-sanctioned oil after a US blockade cut off Iranian exports, and their rush to use up crude import quotas by year-end, further increased tanker demand.
Asian refiners had held back purchases in recent weeks due to high costs, depressing spot prices, but the sharp fall in freight rates has changed the economics of long-haul crude trade, with West African free-on-board offers exceeding $40 per barrel over ICE Brent during October 2026, while Brazilian crude offers rose above $20 per barrel over ICE Brent, before the freight correction made these barrels more competitive. Brazilian Tupi crude last traded at a premium of 7-8 per barrel to December dated Brent for January arrival, versus deals at premiums near $20 last month, reflecting the broader reset in Atlantic Basin crude pricing.
The shift in Asian buying patterns could support demand for African crude oil by reducing the cost of transporting shipments to Asia, one of the main destinations for the continent’s petroleum exports, with shipping costs affecting the price refiners pay for imported crude and a reduction of $5 to $10 per barrel capable of influencing purchasing decisions involving millions of barrels. The renewed interest from Asian buyers comes at a critical time for African producers, who have faced declining export volumes to African markets and shifting investment patterns, with some farmers and producers relocating operations to other African markets in response to export restrictions and market pressures.
The challenge for African producers will be to capitalise on the improved freight economics by securing long-term contracts and building relationships with Asian refiners, rather than relying on short-term price movements, with the volatility in freight rates highlighting the need for producers to develop more resilient export strategies. The outcome of current negotiations between African producers and Asian buyers will likely determine whether the recent surge in demand translates into sustained market access or remains a temporary response to changing freight conditions.
Africa Presents is a Pan-African digital magazine and monthly publication covering politics, business, economy, culture, tech, and the stories shaping Africa and its diaspora. Visit africapresents.com and follow @AfricaPresents for daily coverage and monthly themed magazine editions.




Leave a comment